44AD on Commission Income: A Real 143(2) Scrutiny Case
A real 44AD scrutiny case from our practice, by CA Naveen Pandey
44AD and Commission Income: 5 Key Facts
- 44AD does not apply to commission or brokerage
- Section 58 replaces 44AD from tax year 2026-27
- Commission earners file ITR-3, not ITR-4
- Books rebuilt in about 2 months
- Case closed with no addition
Section 44AD does not apply to commission income. The law keeps out anyone earning commission or brokerage, and anyone running an agency business. If you earn commission and filed your return under 44AD, the Income Tax Department can question it through a scrutiny notice under Section 143(2).
From tax year 2026-27, Section 58 of the Income-tax Act, 2025 replaces 44AD and keeps the same exclusion. Below is a real case from our practice: a 44AD claim on commission income, a scrutiny notice, no proper books, and a case that closed with no addition.
Who Cannot Use Section 58 (formerly 44AD)?
Section 44AD lets a small business declare a fixed share of turnover as income (8%, or 6% for digital receipts) without keeping detailed books. Section 44AD(6) of the Income-tax Act, 1961 says the scheme does not apply to:
- a person carrying on a profession covered by Section 44AA(1), such as legal, medical, engineering or accountancy work
- a person earning income in the nature of commission or brokerage
- a person carrying on any agency business
So commission agents, brokers and agency businesses cannot declare a presumptive figure and stop there. They have to work out their actual income. Section 58 of the 2025 Act carries the same rule forward for tax year 2026-27 onwards. Returns for FY 2025-26 and earlier years are still assessed under the 1961 Act.
Why Commission Earners Still File Under 44AD
ITR-4 (Sugam), the form for presumptive income, is short, and 44AD needs no detailed books. That makes it look like the easy option. Many small businesses also earn commission alongside sales and purchases, and the commission part is easy to overlook when the return is filed.
The Department can see the gap. GST returns, AIS and Form 26AS show what you received and from whom. When the nature of income does not fit the scheme claimed, a scrutiny notice can follow.
A Real Case From Our Practice: 44AD on Commission Income
A client came to us after receiving a notice under Section 143(2) for AY 2024-25. He had filed his return under Section 44AD, but his income was in the nature of commission. He also had sales and purchases.
The Department questioned his eligibility for the scheme and asked him to justify the income he had declared.
We asked for his bank statements and his sales and purchase records. That is where the real problem showed up:
- He tracked sales and purchases only in Excel sheets. There were no proper books of account.
- His sales bills did not follow a continuous series, so we could not rely on the sales record as it stood.
- His bank accounts had a large number of transactions, and he could not recall the nature of many of them.
Once the Department questioned the 44AD claim, the burden was on him to explain his actual income and the source of every significant bank entry. Without books, unexplained credits risked being added to his income, on top of the eligibility issue.
How We Rebuilt the Books for the Scrutiny Reply
Collecting his records took about two weeks. We did not rely on the incomplete Excel sheets. We rebuilt the accounts in four steps:
- 1Matched sales and purchases with official data.We pulled the data on the GST portal, AIS and Form 26AS and reconciled it with his Excel sheets. This gave a verified base for turnover and purchases that the Department could check against its own data.
- 2Recorded everything in proper books.Using the reconciled figures, we prepared books of account for the year. We recorded each sale and purchase from verified documents, not from the broken bill series.
- 3Mapped every bank entry.We matched each entry in the bank statements to a recorded transaction: sales receipts, purchase payments, commission income, expenses and transfers between his own accounts.
- 4Traced the entries he could not remember.For these, we worked through amounts, dates, counterparties, repeat patterns and links to invoices or portal data. This let us identify and support the nature of each one instead of leaving it unexplained.
The reply and the outcome
We then drafted the reply on the basis of these books. It showed his actual income computed from the books in place of the presumptive figure. It gave a full reconciliation of turnover with the portal data and explained every bank credit and debit.
| Stage | Time taken |
|---|---|
| Records collected and gaps found | About 2 weeks |
| Books rebuilt (portal reconciliation, bookkeeping, bank mapping) | About 2 months |
| Reply filed on the basis of the books | After the books were ready |
| Case closed | About 1 year from the start |
Outcome: the case closed in about a year with no addition. His income as per books was accepted. The case was handled under the Income-tax Act, 1961, as it related to AY 2024-25.
We do this kind of rebuild for clients who are behind on their books; see our accounting and bookkeeping services in Delhi.
What Should a Commission Earner Do Instead?
Commission income is taxed on actual profit, not on a presumptive figure. In our practice, these are the points we check for a client who earns commission:
| Point | What applies to commission income |
|---|---|
| Income declared | Actual income worked out from books, not 8% or 6% of receipts |
| Books | Proper books of sales, purchases, commission, expenses and bank entries |
| ITR form | ITR-3 (ITR-4 is only for presumptive income under 44AD, 44ADA or 44AE) |
| Tax audit | Section 63 (formerly 44AB) when turnover crosses Rs 1 crore, or Rs 10 crore if cash receipts and cash payments are each within 5% |
| Matching | Turnover in the return matches GST returns, AIS and Form 26AS |
Bank entries need the most care. A credit you cannot explain is where the real tax exposure lies, more than the 44AD claim itself.
Got a 143(2) Notice? What to Do First
A notice under Section 143(2) means your return has been picked for scrutiny. It can be issued only within three months from the end of the financial year in which the return was filed, so check the dates first. These steps help you prepare the reply:
- Read the notice on the portal. Log in to incometax.gov.in and open e-Proceedings under Pending Actions. Note the questions asked and the due date.
- Collect your records. Keep bank statements for all accounts, sales and purchase bills, GST returns, AIS and Form 26AS ready.
- Reconcile before you reply. Match the turnover in your return with GST and AIS data, and list any difference with its reason.
- Explain every large bank credit. Link each one to a sale, a loan, a transfer from your own account or another known source, with documents.
- Reply on the portal with documents. Answer each question in the notice, attach the reconciliation and books, and keep the acknowledgement.
There is no single prescribed format for a 143(2) reply. The reply follows the questions in the notice. In our practice, a short reply with clear documents works better than a long letter without them. For notices that go further, see our income tax litigation services.
Frequently Asked Questions
Can a commission agent use Section 44AD?
No. Section 44AD(6) of the Income-tax Act, 1961 excludes a person earning income in the nature of commission or brokerage, and a person carrying on agency business. A commission agent has to declare actual income from books and file ITR-3. Section 58 of the Income-tax Act, 2025, which replaces 44AD from tax year 2026-27, keeps the same exclusion.
I earn from trading and also from commission. Can I use 44AD for the trading part?
The exclusion in Section 44AD(6) is written for “a person earning income in the nature of commission or brokerage”, not only for the commission amount. In the case above, the client had sales and purchases as well as commission, and the Department questioned his eligibility for the whole scheme. Show this mix to your CA before you choose the scheme.
What happens if I wrongly claimed 44AD on commission income?
The Department can question the claim in scrutiny under Section 143(2) and ask you to justify your income. You will then need your actual income from books and an explanation for your bank entries. Credits you cannot explain risk being added to your income. With rebuilt books and full reconciliation, our client’s case closed with no addition.
Can I file an updated return after receiving a 143(2) notice?
No. An updated return under Section 139(8A) cannot be filed for a year where assessment or reassessment is pending or has been completed. Once a 143(2) notice starts the assessment, the way forward is a reply with proper books and reconciliation, not an updated return.
Which ITR form should a commission earner file?
ITR-3, if the commission is business income of an individual or HUF. ITR-4 (Sugam) is only for income declared on a presumptive basis under 44AD, 44ADA or 44AE, so it does not fit commission income.
Is there a fixed format for a 143(2) notice reply?
No single format is prescribed. The notice on the e-Proceedings tab lists the questions and the documents the officer wants. Your reply should answer each question in order, with the reconciliation, books and bank explanations attached. Keep a copy of every submission and its acknowledgement.
Sources: ITR-4 (Sugam): who can file, incometax.gov.in · ITR-3: who can file, incometax.gov.in
Reviewed by CA Naveen Pandey on 10 November 2026
Received a 143(2) notice, or unsure about a 44AD claim on commission income?
Bring your notice, bank statements and GST returns to our Vikaspuri office, and we will go through them with you.
Book a Consultation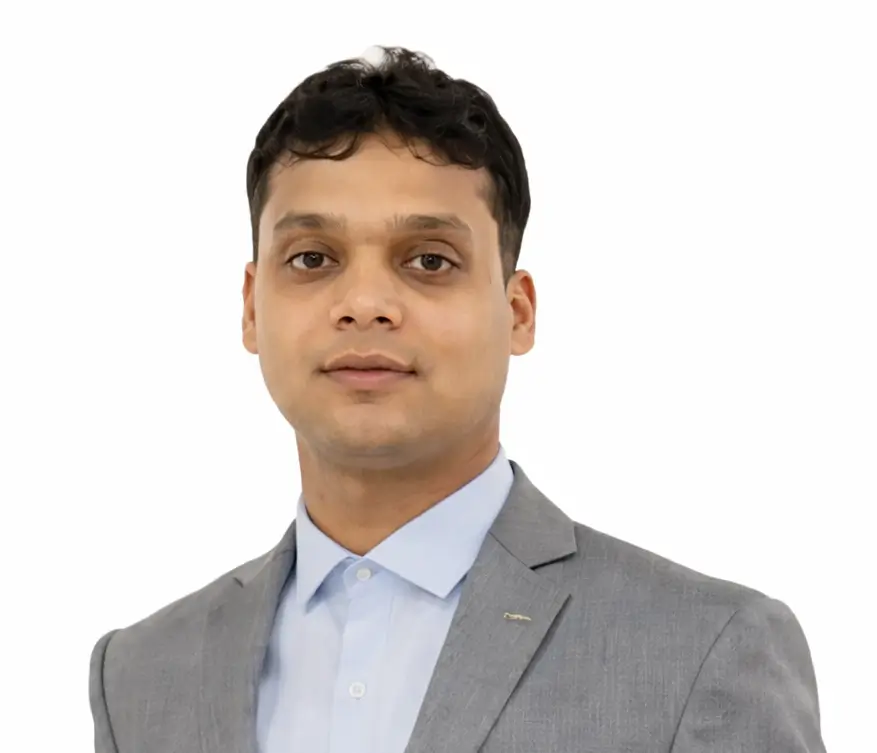
CA Naveen Pandey
CA | CS | CMA with AIR 5 | B.Com, Delhi University | ICAI Registered
CA Naveen Pandey is the founder of Naveen Pandey & Associates, a Vikaspuri-based chartered accountancy firm serving 100+ Dwarka clients since 2014. He holds CA, CS, and CMA qualifications simultaneously — clearing CA Final in the first attempt in 2012. He specialises in ITR filing, NRI taxation, GST compliance, and transfer pricing. CA Naveen Pandey personally reviews every client file before it is assigned to the team.
Our Services for Tax and Accounts
Help with notices, books and returns for small businesses
Open All 7 Days, Including Sunday
Our Vikaspuri office is open every day. Mon-Fri 10 AM-9 PM, Sat 10:30 AM-9:30 PM, Sun 11:30 AM-9 PM.